
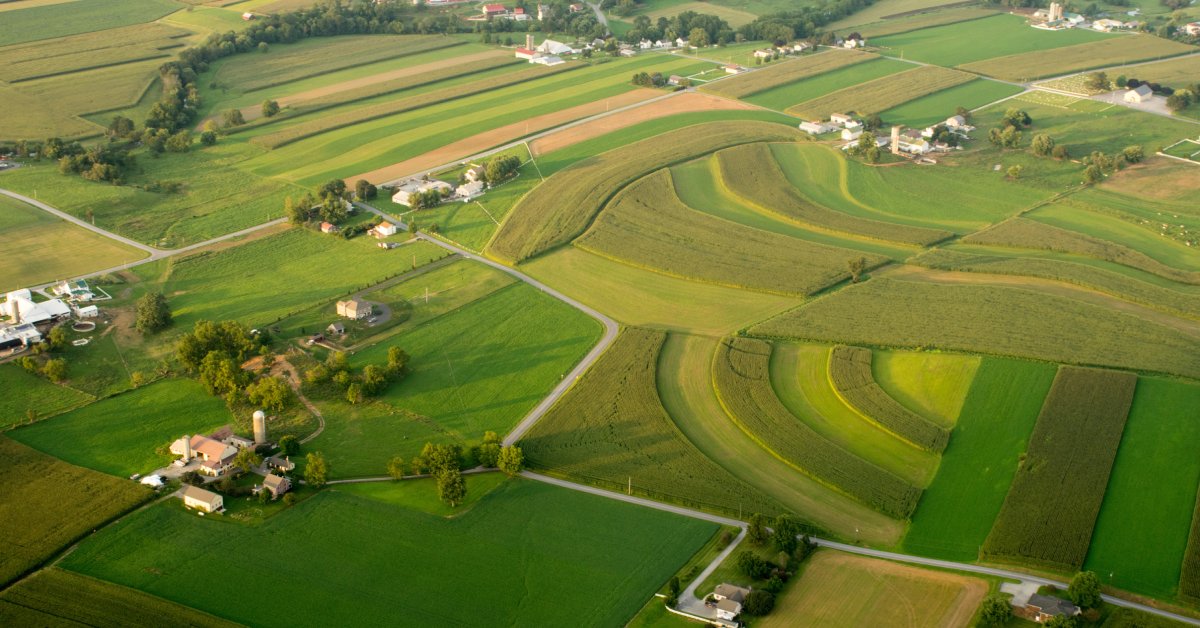
Farm loans are valuable resources that help farmers maintain and grow their agricultural operations. Choosing between short-term and long-term loans can feel like a major decision. Nonetheless, understanding their differences is the best way to an informed choice.
Each loan type serves a different purpose to suit the borrower’s specific financial needs. To determine if a short-term or long-term farm loan is right for you, continue reading to learn about their characteristics.
Purpose of the Loan
Short-term loans meet immediate financial needs and keep your operations running smoothly. People often use these loans for essential expenses like purchasing seeds, repairing equipment, or preparing for extreme weather.
Long-term loans are better suited for large, strategic investments. The additional funds might help farmers buy land to expand the farm, construct new buildings like barns, or acquire heavy machinery that will improve the farm’s efficiency.
Loan Duration
The repayment period is one of the key differences between short-term and long-term loans. Short-term loans are typically repaid over a few months or within the same year, depending on the terms of the agreement. They are ideal for addressing immediate or seasonal financial needs.
Long-term loans commonly span several years or decades. This gives borrowers more time to repay the loan while allowing them to make substantial investments that may take time to generate returns.
Interest Rates
Interest rates can also vary significantly between short-term and long-term loans. Short-term loans often feature slightly higher interest rates because of the short repayment period and the immediate nature of the borrowing.
Long-term loans generally have lower interest rates. Due to their extended duration, the total interest accrued over time may be higher than a borrower would pay for a short-term loan. It’s important to calculate the long-term cost of the loan including interest, not just the monthly payment amount.
Repayment Structure
Short-term loans usually require faster repayments. These might involve lump-sum payments or regular, quicker installments, making them a good choice for meeting seasonal or short-term financial needs. Long-term loans offer more structured repayment plans with monthly, quarterly, or annual payments. This format makes repayment plans more manageable for larger investments since borrowers can spread out the payments over a long period.
Risk Factors
The risks involved in short-term and long-term loans also differ. Short-term loans carry lower risk in terms of commitment, as you pay them off relatively quickly. This makes them a less risky option for smaller, immediate needs. Long-term loans, while beneficial for major investments, involve greater risk due to their longer commitment period. Market fluctuations, changes in interest rates, or unforeseen circumstances over several years can impact your ability to repay.
Approval Process
Short-term loans have a quick and simple approval process. Because the borrowed amounts involve less risk for the lender, you can expect a faster turnaround with minimal paperwork. Long-term loans are more likely to require extensive documentation, including financial history, a business plan, and collateral details.
Flexibility of Use
The flexibility of short-term loans in terms makes them ideal for covering immediate working capital needs, such as purchasing supplies and handling unexpected costs. Farmers who choose long-term loans typically have specific purposes outlined in the loan agreement, like land acquisition or equipment purchases. Lenders may require borrowers to use the funds in ways that align with the initial application.
Impact on Cash Flow
Short-term loans can temporarily tighten your cash flow due to their quicker repayment timelines. For instance, if you’re repaying the loan within a few months, you’ll need to carefully manage your expenses to avoid financial strain.
In contrast, long-term loans tend to have a minor impact on the cash flow, as payments are spread out over an extended period. This payment procedure makes them a more viable option for large investments that don’t yield immediate returns.
The Best Loan for Seasonal Needs
To address seasonal needs, short-term loans are particularly useful. For example, during planting season, you might need funds to purchase seeds and fertilizer. These loans ensure that your farm operations run smoothly until you start seeing returns from your harvest. They are a quick and efficient way to cover essential costs and keep your business on track.
The Best Loan for Expanding Operations
If you’re planning to grow your farm or invest in new opportunities, a long-term loan is often the better choice. These loans provide the funds to make immense changes, like acquiring new land, upgrading the infrastructure, or purchasing expensive machinery. With manageable repayment terms spread over many years, long-term loans allow farmers to invest confidently in the farm’s future without carrying the burden of immediate repayment.
Collateral Requirements
Collateral requirements can vary, but both short-term and long-term loans often require some form of security. Short-term loans may require low-value collateral since the borrowed amounts are small. Long-term loans, because they involve larger sums and extended repayment periods, typically require higher-value collateral, such as real estate or expensive equipment. It’s important to understand what you’re putting up as collateral and its implications if you’re unable to repay the loan.
Budget Planning
Managing your budget is crucial when taking on any loan. Short-term loans demand precise budget management due to their tighter repayment schedules. Before signing a contract, make sure you can repay the loan without disrupting other financial obligations.
Long-term loans, on the other hand, give borrowers more time to develop and adjust their repayment strategies. Aligning payments with revenue cycles can make long-term loans more manageable over time.
Access to Credit
Both short-term and long-term loans can impact your credit score. Short-term loans help people build a reliable credit profile in a short period of time. Long-term loans take longer to reflect on your credit score. Nevertheless, they can demonstrate financial stability and responsibility when people make payments consistently. Both types of loans play a role in building a strong credit record, which can benefit future borrowing.
Tailored Choices
Ultimately, the decision between a short-term and a long-term loan depends on your specific needs and goals. Short-term loans are great for immediate, smaller needs, while long-term loans are better suited for strategic growth and larger investments.
By carefully considering your financial objectives, repayment capacity, and the nature of your farming operations, you can choose the loan that best supports your success. It’s all about finding the right fit for your unique circumstances.
Understanding the differences between short-term and long-term farm loans will help you make the right financial decision for your agricultural operations. By evaluating your current priorities and future goals, you can confidently choose the farm loan that aligns with your business strategy.
Let Farm Plus Financial help. Whether you’re seeking short or long-term loans, we can offer the support you need to keep your farm thriving.